Exploring the Rise of Multigenerational Living by 2026
5 October 2026
Multigenerational living is not a new idea. For most of human history, it was the default. What is new is the speed at which it is returning to the center of housing decisions in developed economies, and how that return is reshaping everything from floor plans to mortgage underwriting to municipal zoning. By 2026, this shift will not look like a temporary reaction to high prices. It will look like a structural change in how households form, how homes are designed, and how buyers evaluate property.
If you are a buyer, seller, builder, lender, or investor, this matters more than most market forecasts. The demand curve for housing is being redrawn by who lives together, not just how many people need shelter. Understanding why multigenerational living is rising, where it works, where it fails, and what to do about it will separate informed decisions from expensive guesses.
What Multigenerational Living Actually Means
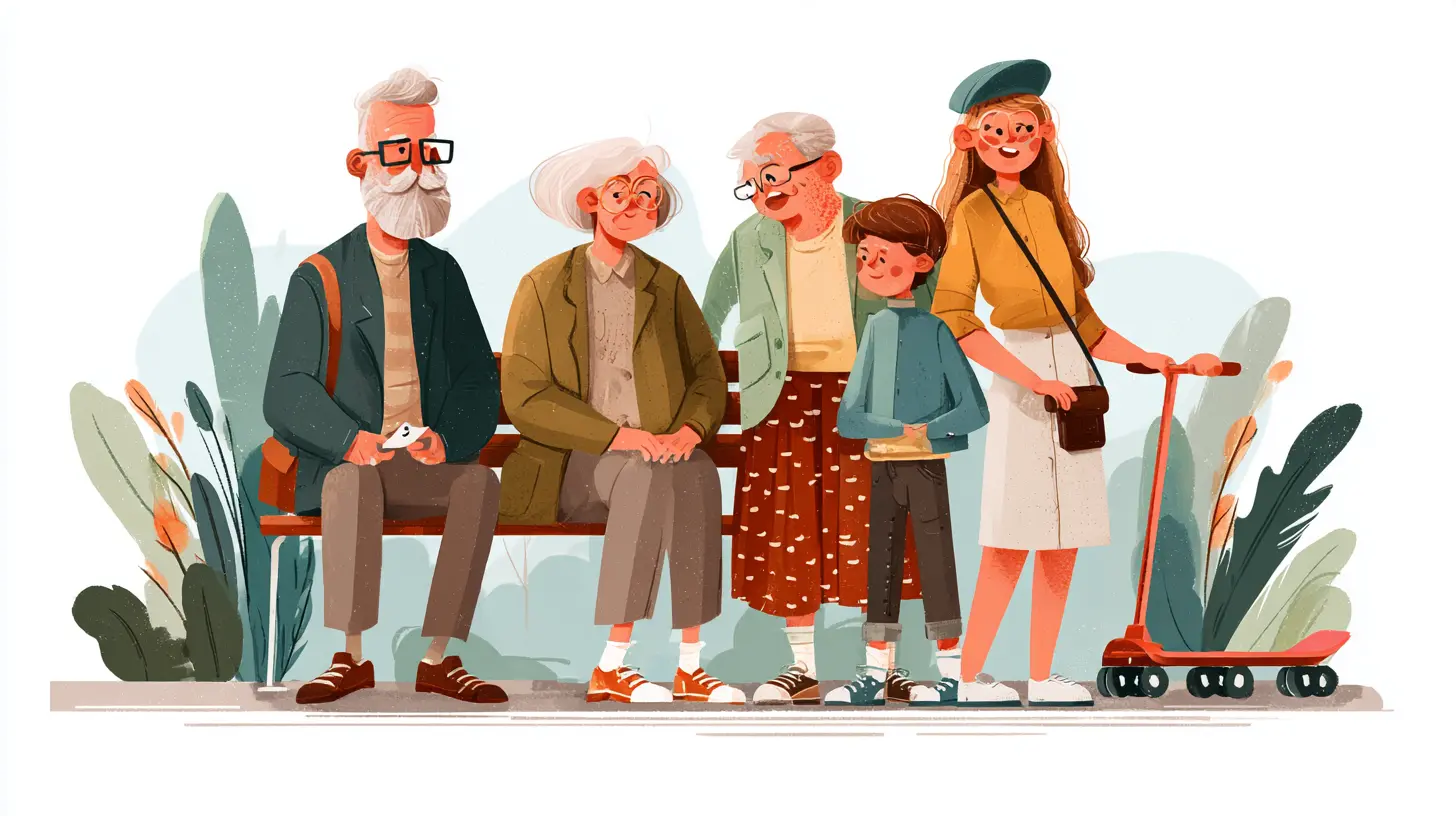
The term gets used loosely, so it helps to draw boundaries. A multigenerational household contains at least two adult generations, or one generation plus a grandparent, living under one roof. That is different from a multigenerational property, which might be a single home with a separate suite, a duplex, or an accessory dwelling unit on the same lot.This distinction matters because the housing response differs. Some families want shared walls and shared meals. Others want proximity with privacy. A granny flat in the backyard and a converted basement are both multigenerational solutions, but they serve different emotional and financial needs.
There is also a difference between choosing to live together and needing to. A household formed because childcare costs exceed one parent's income is not the same as a household formed because adult children want to save for a down payment while helping aging parents. Both are rising, but they respond to different incentives and different design solutions.
The Forces Pushing Households Together
Several pressures are converging at once, and none of them look temporary.Housing Affordability and the Math of Staying Put
In many metropolitan areas, the gap between median home prices and median incomes remains wide. When a single household cannot comfortably carry a mortgage, taxes, insurance, and maintenance on one income, pooling resources becomes rational rather than sentimental. Two adults contributing to one housing cost is not a compromise. It is arithmetic.This is not only about young adults. Retirees on fixed incomes face rising property taxes, insurance premiums, and utility costs. Staying in a home they own often requires either a roommate, a family member, or a downsizing move that may not exist in their market. Multigenerational arrangements solve a cash-flow problem that has no easy alternative.
Childcare Costs and the Return of the Extended Family
Childcare expenses in many regions rival or exceed rent. When grandparents provide care, the household saves money that would otherwise leave the family permanently. That saving is often the difference between one parent staying in the workforce and leaving it.There is a second-order effect here. Grandparents who provide care often receive informal support later, from transportation to health monitoring. The arrangement functions as a private, non-market care system. It is efficient, but it is also fragile, because it depends on health and goodwill rather than contracts.
Aging in Place and the Limits of Senior Housing
Most older adults say they want to remain in their homes. The senior housing industry offers options, but they are expensive, and supply in many markets is tight. Multigenerational living offers a middle path: stay connected to family, avoid institutional care for as long as possible, and preserve assets for heirs.The catch is that most existing homes were not built for this. A two-story colonial with bedrooms upstairs and a full bathroom on the second floor is a poor fit for someone with mobility challenges. Retrofitting is possible, but it is not cheap, and it is not always permitted by local codes.
Cultural Continuity and the Limits of Assimilation
For many immigrant and first-generation families, multigenerational living is not a response to economics. It is the norm. As those communities grow, their housing preferences shape demand in ways that mainstream real estate analysis often misses. A market that only builds for nuclear families leaves money on the table.Remote Work and the Geography of Proximity
Remote work loosened the tie between where people live and where they earn. That made it easier for adult children to move back near parents without sacrificing careers. It also made it easier for parents to relocate near children. The result is a slower, more deliberate reshuffling of households that does not show up clearly in migration statistics.
Why 2026 Is a Tipping Point, Not a Blip
Forecasts are easy to get wrong, so it is worth being precise about what is changing.First, the demographic math is locked in. Large cohorts are entering the ages when care needs rise and when adult children typically reconsider living arrangements. That pressure does not disappear if prices fall. It intensifies.
Second, the housing stock is adapting. Builders who spent decades producing primarily three-bedroom, two-bath suburban homes are experimenting with dual-primary suites, casitas, and flexible floor plans. Lenders are slowly catching up with loan products that recognize rental and shared-income arrangements. Zoning reforms in a growing number of jurisdictions have made accessory dwelling units easier to permit.
Third, the financial infrastructure is maturing. Shared mortgages, family loans, and co-ownership agreements are becoming more common, though they remain unevenly regulated. As these tools become familiar, the stigma around pooling resources fades.
None of this guarantees that every market will see the same trajectory. High-cost coastal metros will feel it first. Rural areas with cheap housing may see less pressure. But the direction is clear.
The Housing Types That Serve Multigenerational Households
Not all multigenerational housing is the same, and choosing the wrong type is one of the most common and costly mistakes.The Single-Family Home With a Converted Suite
This is the most common approach. A basement, garage, or spare bedroom becomes a living space with its own entrance, kitchenette, and bathroom. It is often the cheapest option because it uses existing square footage.The trade-offs are real. Conversion costs vary widely depending on plumbing, electrical, and egress requirements. Some jurisdictions require permits and inspections that can take months. And a converted suite may not appraise as a separate unit, which limits financing options.
The Accessory Dwelling Unit
An ADU is a separate structure on the same lot, typically a detached cottage, a converted garage, or a second unit above a garage. It offers more privacy than an interior conversion and can generate rental income if the family situation changes.ADUs are not universally allowed. Setbacks, lot coverage limits, parking requirements, and utility connections can kill a project before it starts. Where they are allowed, they often add significant value, but that value depends on local rental demand and the legality of the unit.
The Duplex, Triplex, or Multiplex
Small multifamily buildings allow families to live in separate units while sharing a roof and a mortgage. This is the most flexible option because units can be rented to non-family tenants if needed.The downside is complexity. Financing is different, insurance is different, and disputes between co-owners can become legal disputes. This option works best when there is a clear written agreement covering expenses, decision-making, and exit terms.
The Co-Housing and Intentional Community Model
A smaller but growing category involves multiple families sharing common spaces and sometimes common ownership. These arrangements can reduce costs and isolation, but they require governance structures that most families are not prepared to create or maintain.The "Two Homes, One Lot" Arrangement
Some families buy two adjacent properties or a property with two existing homes. This preserves privacy while maintaining proximity. It is often the most expensive option, but it avoids the daily friction of shared walls.The Financial Case, With Honest Numbers
The financial appeal of multigenerational living is real, but it is frequently overstated.On the positive side, pooling resources can reduce housing cost per adult, lower childcare expenses, and defer or avoid the cost of assisted living. It can also improve credit access when incomes are combined, though lenders do not always count non-borrower income.
On the negative side, the costs are often hidden. Renovations, permit fees, higher utility bills, added insurance, and the opportunity cost of caregiving labor all reduce the net benefit. Family members who provide care often reduce their own earning capacity, which is a cost that does not appear on any spreadsheet.
The honest framing is this: multigenerational living is often financially superior to the alternatives available, not because it is cheap, but because the alternatives are more expensive. That is a meaningful distinction. It means the arrangement is worth doing when the alternatives are bad, and less compelling when they are not.
There is also a tax dimension. Depending on jurisdiction, families may be able to claim dependents, deduct medical expenses, or exclude some rental income. These rules vary widely and change often. Anyone making a significant decision should consult a tax professional rather than rely on general advice.
Design and Renovation: What Actually Works
The difference between a multigenerational arrangement that lasts and one that collapses is usually design, not affection.Separate Entrances Are Not Optional
Privacy is the single strongest predictor of success. A separate entrance, even if it is rarely used, changes the psychology of the arrangement. It signals that each household has autonomy.Sound Isolation Matters More Than Square Footage
Families consistently underestimate noise. Shared walls, shared floors, and open floor plans amplify conflict. Investing in insulation, solid-core doors, and strategic layout is often more valuable than adding a bedroom.Kitchens Are the Pressure Point
Two kitchens, or one kitchen plus a kitchenette, reduce daily friction dramatically. Shared cooking schedules, dietary differences, and cleanup expectations are among the most common sources of tension.Bathrooms Should Be Counted Carefully
A ratio of one full bathroom per adult household is a reasonable target. Fewer than that creates scheduling conflict that no amount of goodwill can solve.Accessibility Should Be Planned Early
If the arrangement involves aging parents, wide doorways, zero-threshold showers, and main-floor sleeping arrangements are not luxuries. They are requirements. Retrofitting later is more expensive and more disruptive.Outdoor Space Is a Release Valve
A patio, garden, or even a well-designed balcony gives household members a place to be alone without leaving the property. This is one of the most underrated design features in multigenerational homes.Legal and Financial Structures That Prevent Disaster
Most multigenerational arrangements fail for legal and financial reasons, not interpersonal ones. The following structures reduce risk.Written Co-Ownership Agreements
If more than one party contributes to a down payment or mortgage, a written agreement should specify ownership percentages, contribution obligations, decision-making authority, and exit terms. Verbal agreements are worthless when relationships sour or when someone dies.Estate Planning and Inheritance
Parents who add an adult child to a title for convenience may unintentionally disinherit other children or trigger tax consequences. Estate attorneys see this mistake constantly. A trust or a life estate is often a better tool.Rental Agreements Between Family Members
Even when no money changes hands, a written occupancy agreement clarifies expectations. It can also protect the homeowner's insurance coverage and the occupant's legal status.Insurance Review
Standard homeowner policies may not cover a separate dwelling unit, a home-based business, or a long-term occupant who is not a named insured. Reviewing coverage before the arrangement begins is far cheaper than discovering gaps after a loss.Financing That Matches the Reality
Traditional mortgages assume one borrower, one household, one income. Multigenerational buyers often need portfolio loans, co-borrower arrangements, or family loans documented properly. Lenders are slowly adapting, but the burden is on the borrower to ask the right questions.
Common Mistakes and Misconceptions
Several beliefs about multigenerational living are widespread and wrong."It always saves money." It often does, but not always. Renovation costs, higher utilities, and caregiving labor can erase the savings. Run the numbers before committing.
"Family will figure it out." Families that do not discuss money, schedules, and boundaries in advance almost always struggle. The conversation is uncomfortable. It is also necessary.
"We can always convert the basement later." Conversion may be prohibited by code, impractical due to ceiling height or drainage, or far more expensive than expected. Verify before you buy.
"It is a temporary arrangement." Many families intend to live together for a year and stay for a decade. Design and legal structures should assume a longer timeline.
"It hurts resale value." This depends entirely on the market. In some neighborhoods, a legal ADU or a well-designed in-law suite adds value. In others, it narrows the buyer pool. Research local comparables rather than assuming.
What Buyers, Sellers, and Investors Should Do Now
The practical implications differ by role.If You Are Buying
Decide in advance whether you need a legal second unit or simply extra space. Legal units cost more but offer rental income and financing flexibility. Check zoning, permit history, and insurance implications before making an offer. Walk the property at different times of day to assess noise and privacy.If You Are Selling
Document any improvements, permits, and rental history. A legal, well-built ADU or in-law suite can be a strong selling point if it is marketed to the right buyers. Do not assume every buyer will value it. Price accordingly.If You Are Building
Design for flexibility. A floor plan that can function as one household or two is more valuable than one that only works for a single configuration. Include rough-in plumbing and electrical for future kitchenettes even if you do not install them now.If You Are Investing
Multigenerational demand is not uniform. It is strongest in expensive metros, in areas with aging populations, and in communities with strong extended-family norms. Underwrite accordingly, and do not assume that a property that works for one household will work for two without modification.
What to Watch Through 2026
Several signals will indicate how far this trend goes.Zoning reforms that legalize ADUs by right, rather than by discretionary permit, will accelerate supply. Lending products that recognize shared households will reduce friction. Insurance products that cover multi-unit owner-occupied properties will determine whether some arrangements are financially viable.
On the demand side, watch childcare costs, elder care costs, and interest rates. When those rise, multigenerational demand rises with them. When they fall, some households will separate again, though not all.
The most important thing to watch is not a statistic. It is the floor plan. When mainstream builders start offering dual-primary suites and legal second units as standard options rather than custom upgrades, the trend has moved from niche to normal.
A Final Word on Honesty
Multigenerational living is not a solution to every housing problem, and it is not right for every family. It works when the financial math is sound, the design supports privacy, and the legal structure prevents ambiguity. It fails when families assume that love replaces planning.By 2026, more households will test this arrangement than at any point in recent memory. Some will thrive. Others will regret it. The difference will rarely come down to how much they love each other. It will come down to how carefully they planned before they signed anything.
all images in this post were generated using AI tools
Category:
Housing Market TrendsAuthor:
Lydia Hodge
Discussion
rate this article
1 comments
Cassian McNaughton
Multigenerational living is more than a trend; it's a response to rising costs and shifting family dynamics. Embracing this lifestyle means flexibility, support, and unity. By 2026, expect it to redefine our communities and reshape housing markets.
October 5, 2026 at 3:24 AM